 John Jevi dela Cruz
Small business restructuring is not only something to think about when a company is already in crisis. For many businesses, the most useful time to act is earlier, while there are still choices available.
That matters now because ASIC released a new five-year review of the small business restructuring process on 11 November 2026. The review examined 6,606 restructuring appointments from 2021 to 2026. Its message is simple: directors should monitor financial pressure and seek advice early.
For business owners, this is less about insolvency jargon and more about recognising what the numbers are already saying. Falling cash reserves, overdue suppliers and growing debt can point to a deeper problem. Repeated short-term fixes are another warning sign.
ASIC’s financial difficulty guidance for directors says early action can preserve more options. It can also reduce the risk of problems becoming harder to solve.
Why Small Business Restructuring Matters Now
ASIC’s latest review found that 76% of appointments moved to a restructuring plan over the five-year review period. It also found that approval rates fell over time, from 87% in 2023–24 to 67% in 2025–26.
The lesson is not that every struggling company should restructure. Directors should not wait until cash has run out or suppliers have lost confidence. By then, debts may already be harder to manage and options may have narrowed.
HarvestWise has previously explained why cash flow needs regular attention. Small business restructuring sits further along the same spectrum. It becomes relevant when ordinary cash-flow fixes are no longer enough.
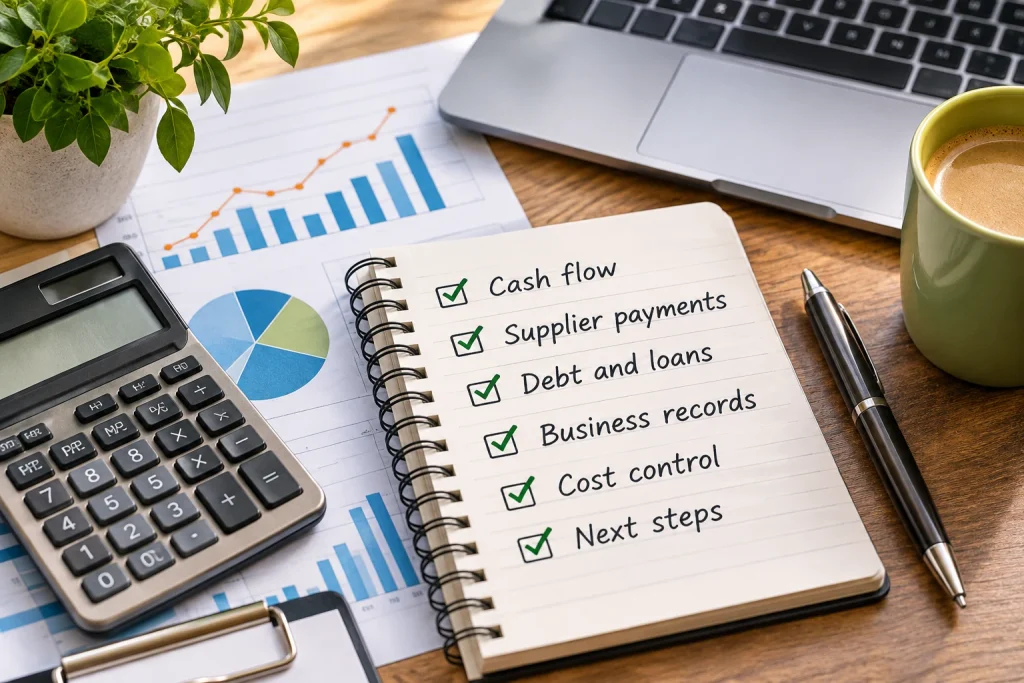
1. Ignoring Tight Cash Because Sales Look Fine
A business can report revenue and still struggle to pay its bills.
That can happen when customers pay slowly or margins are too thin. Inventory can absorb cash, while operating costs may rise faster than prices. The result is a business that looks active but constantly feels short of money.
For small business restructuring, the pattern matters more than one bad week.
If the business repeatedly delays payments or moves money between accounts, pay attention. Using credit just to cover normal costs can also signal a structural problem.
Business.gov.au lists reduced cash flow as a key warning sign of financial trouble. Difficulty paying suppliers, loans or taxes can all point to pressure.
2. Letting Supplier Payments Keep Slipping
One late supplier payment can happen in any business. A pattern is different.
If 14- or 30-day invoices keep stretching to 45 or 60 days, the pattern matters. The business may be using suppliers as an unofficial source of finance.
That can damage relationships quickly.
Suppliers may shorten terms, put the business on cash-on-delivery arrangements or stop supplying altogether. ASIC specifically identifies unpaid creditors outside normal trading terms as a warning sign of financial difficulty.
Track accounts payable ageing every month. Do not look only at the total amount owed. Look at how long each balance has been outstanding and whether the trend is worsening.
3. Using Personal Money as the Default Fix
Owners sometimes inject personal funds to support growth or cover a short-term gap. That is not automatically a problem.
In small business restructuring, the warning sign appears when personal money becomes the normal solution to operating losses.
Examples include using personal savings to pay wages or putting supplier bills on a personal credit card. Refinancing personal assets to cover recurring costs is another warning sign.
ASIC identifies reliance on personal funds as a common sign that financial pressure is building.
If owner funding is increasing, record it clearly and ask why the business cannot support itself from normal operations. More money does not fix an underlying margin, pricing or debt problem by itself.
4. Adding Debt Without a Clear Repayment Plan
Borrowing can support a healthy business. In small business restructuring, the issue is whether the debt has a realistic purpose and repayment path.
Warning signs include using one facility to repay another or reaching overdraft limits. Missing loan repayments and borrowing for recurring operating costs also matter.
ASIC’s insolvency guidance lists increasing debt, finance problems and loan defaults among common indicators of financial difficulty.
Directors should know the total amount owed, repayment dates and interest costs. They should also know what security is provided and whether expected cash flow can cover the commitments.
If those answers are unclear, the debt position needs review before another facility is added.
5. Letting the Books Fall Too Far Behind
Poor records do more than make tax time harder. They can hide financial stress until it becomes urgent.
Reliable decisions are difficult when bank reconciliations are months behind. Incomplete supplier balances and uncollected customer debts make the picture worse.
ASIC lists incomplete records and disorganised accounting procedures as warning signs. The absence of cash-flow forecasts is another.
HarvestWise’s article on ongoing accounting support explains why current records matter throughout the year. They are useful well before a return or BAS is due.
Before considering small business restructuring, get the numbers current enough to understand what is actually happening.
6. Waiting for One Big Job to Save the Business
Hope is not a cash-flow strategy.
A major contract, asset sale or new investor can improve a business position. However, relying on one future event while existing debts continue to grow is risky.
ASIC flags reliance on the next big job, sale or contract as a warning sign. One future event should not be the only rescue plan.
Build a forecast that shows what happens if the expected deal is delayed, reduced or never happens.
If the business cannot meet debts without that event, management needs to understand the downside now. Another month of losses can narrow the available options.
7. Running Without a 13-Week Cash-Flow View
A profit and loss statement explains performance. A short-term cash-flow forecast helps answer a different question: can the business meet its obligations when they fall due?
For a business under pressure, a rolling 13-week cash-flow forecast can make problems visible early. It should include expected receipts, wages, supplier payments, finance repayments, rent, tax and super, as well as realistic timing assumptions.
Business.gov.au recommends cash-flow forecasting as a way to recognise financial pressure and act before problems grow.
For small business restructuring, the forecast does not need to be perfect. It needs to be updated often enough to show where the pressure points are.
What ASIC’s Review Says About Small Business Restructuring
ASIC’s November 2026 review shows that small business restructuring is now an established option for eligible companies in financial difficulty.
Across the review period, 76% of appointments progressed to a restructuring plan. Of finalised plans, 64% were fulfilled. ASIC also reported that companies which completed plans often remained registered without another external administration in the following years.
The review also showed that the ATO was a creditor in almost all proposed plans. It accounted for 83% of estimated admissible unsecured claims.
Those figures are useful because they show how financial pressure can build over time. Tax debt may be part of the picture. The broader issue is whether the company has enough cash, control and realistic earnings to meet its obligations.
Read ASIC’s 11 November 2026 restructuring review for the latest findings.
What to Review Before Small Business Restructuring Gets Urgent
If several warning signs are appearing together, start with the basics:
- Bring bookkeeping and reconciliations up to date.
- Prepare an aged receivables and aged payables report.
- Build a realistic 13-week cash-flow forecast.
- List all loans, tax debts and other overdue obligations.
- Review gross margins and pricing by major product or service.
- Identify costs that can be reduced without damaging the business.
- Check whether customers are paying later than before.
- Separate temporary cash pressure from ongoing operating losses.
- Speak with an appropriate adviser before taking on more debt.
This review may show that ordinary cash-flow changes are enough. It may also show that the business needs professional restructuring or insolvency advice.
Small Business Restructuring Is Not a DIY Decision
Formal restructuring has eligibility rules, legal consequences and creditor requirements. It is not simply a budgeting exercise.
If a company may be insolvent, directors should obtain professional advice promptly. The same applies if debts cannot be paid when they fall due. ASIC advises directors to monitor solvency, investigate financial difficulty, obtain suitable advice and act in a timely manner.
An accountant can help get the records current, prepare cash-flow information and identify the financial drivers behind the problem. A registered liquidator or lawyer may also be needed where formal restructuring, insolvency or directors’ legal duties are involved.
How HarvestWise Accounting Can Help
HarvestWise Accounting can help business owners get a clearer picture of cash flow, overdue liabilities and margins. Current reporting can make problems easier to identify and manage.
We can assist with bookkeeping clean-up, reconciliations, management reporting and cash-flow review. The aim is to give you reliable information for the next decision.
If your business is repeatedly short of cash, falling behind with creditors or relying on personal funds, act early. Contact HarvestWise Accounting before another month passes without a clear plan.
Disclaimer
General information only. Financial difficulty, insolvency and restructuring can involve legal and financial consequences that depend on the company’s circumstances. Seek advice from an appropriately qualified accountant, registered liquidator or lawyer before making restructuring or insolvency decisions.